Fed Hikes Ignite CLO Portfolio, Targeting 5.8% Yield Amidst 'Higher-for-Longer' Rates
Context mode is active. Hover over any highlighted term to see its definition. Click a nested term to go deeper.
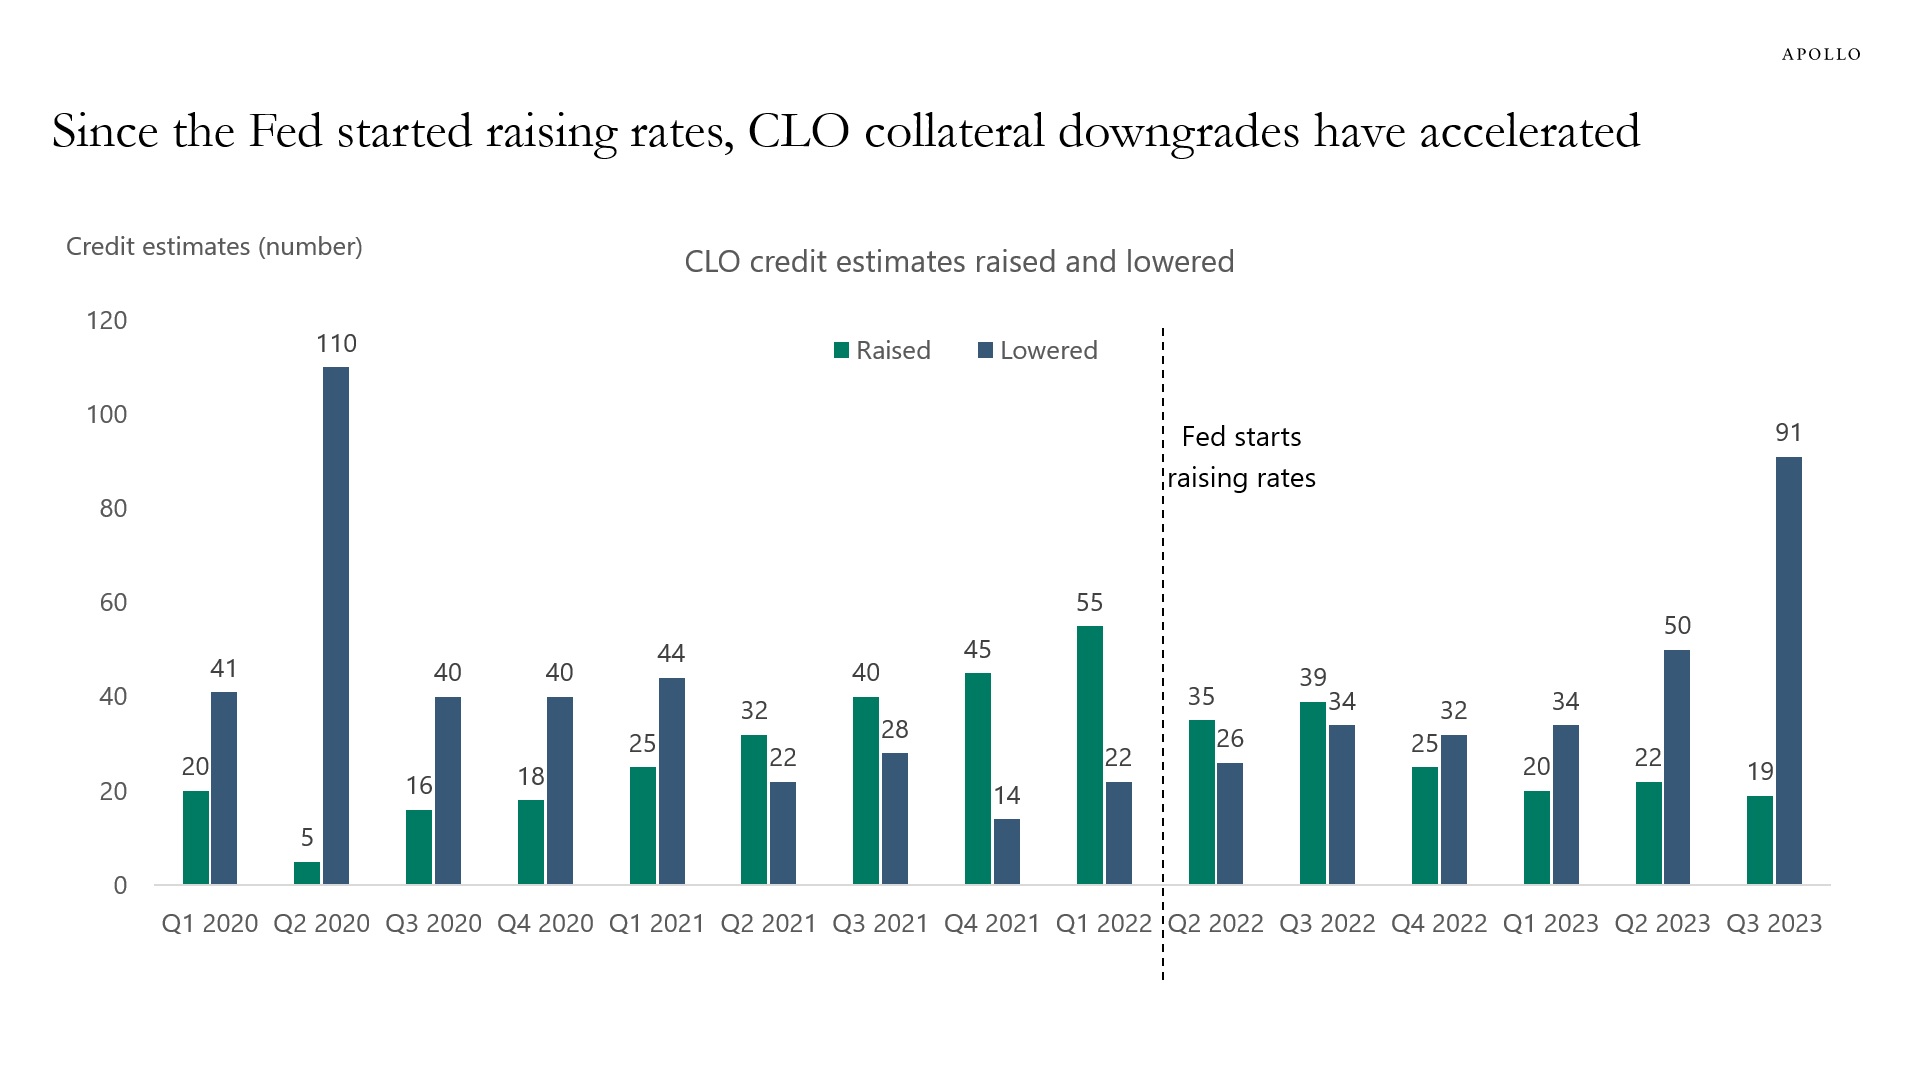
The Federal Reserve delivered its first interest rate hike since 2023 in September 2026, pushing the federal funds rate to a 3.75%-4.00% target range and unexpectedly boosting a specialized eight-fund Collateralized Loan Obligation (CLO) portfolio aiming for a 5.6%-5.8% TTM yield. This move reaffirms the 'higher-for-longer' rate environment, turning the once-dreaded rate hikes into a boon for investors strategically positioned in floating-rate assets. The sharp shift caught many off guard, as market sentiment earlier in the year leaned towards rate cuts, not further tightening. This aggressive stance on monetary policy by the Federal Open Market Committee (FOMC) is a direct response to persistent inflation and a surprisingly resilient labor market, despite rising energy costs and geopolitical tensions. CLO, structured to benefit from rising rates due to their underlying floating-rate leveraged loans, are proving to be a robust shield against interest rate risk while offering attractive yield superior to many traditional fixed-income options. With FOMC projections indicating at least one more rate hike by year-end 2026, the outlook remains favorable for these securitized products. Looking ahead, investors will be keenly watching the Fed subsequent moves and economic data for any signs of a pivot, though Chairman Kevin Warsh has reiterated the Fed commitment to price stability. The continued strength of the US economy and elevated inflation suggest that the window for 'higher-for-longer' rates may extend well into 2027, making actively managed CLO portfolios a critical component for those seeking enhanced income and interest rate protection. The balance between combating inflation and sustaining economic growth will dictate market dynamics, with floating-rate exposures likely remaining a favored strategy.