Infosys Q2 Profit Jumps, But Slashed Outlook Spooks Investors Despite AI Gains
Context mode is active. Hover over any highlighted term to see its definition. Click a nested term to go deeper.
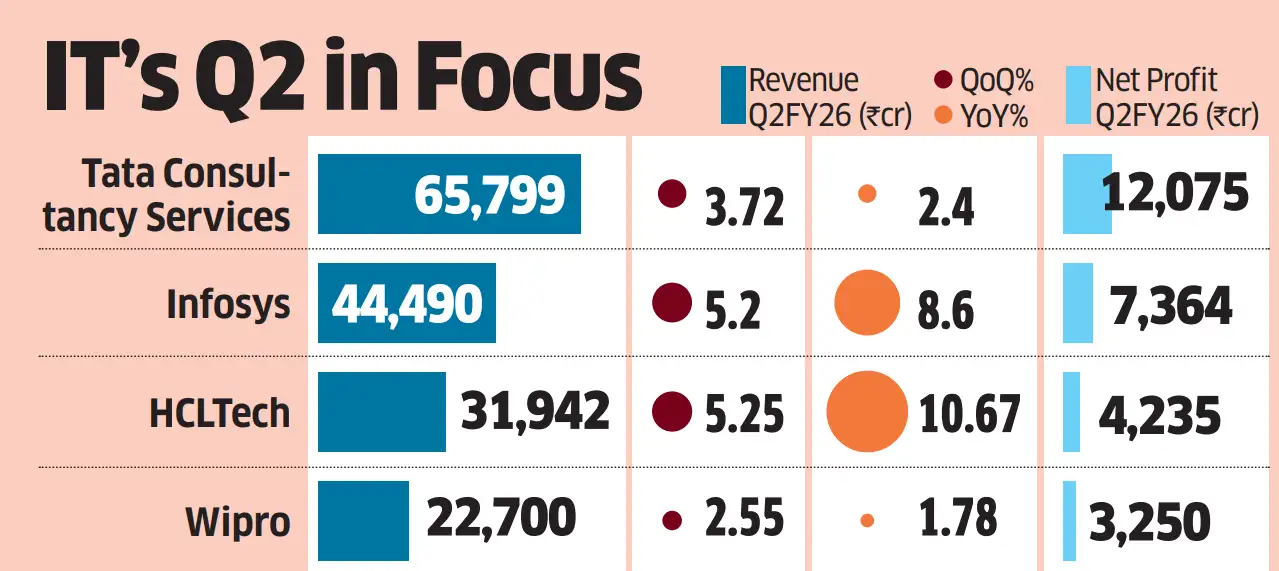
Infosys, India's second-largest IT powerhouse, just dropped its Q2 FY27 numbers, revealing a solid 6% leap in net profit to Rs 7,823 crore and an 11% jump in revenue to Rs 49,244 crore. But here's the kicker: the market wasn't entirely thrilled, as the company simultaneously clipped its full-year revenue growth outlook, sending its shares tumbling by over 5% in premarket trading. This mixed bag comes despite a robust interim dividend of Rs 26 per share and impressive large deal wins, showing the ongoing tension between current performance and future uncertainty in the global tech landscape. This tempered outlook, revised down to 1%-2% in constant currency for the full fiscal year from an earlier 1.5%-3%, reflects the cautious client spending and pricing pressures Infosys is navigating, particularly in North America and Europe. While the broader IT Services Sector is seeing some resilience driven by demand for Artificial Intelligence (AI) and Cloud Modernization, Infosys CEO Salil Parekh highlighted that growth came in below internal expectations due to softer volumes. Still, the company's strategic focus on AI is paying off, with AI-related revenue soaring 29% sequentially and now making up a significant 10.5% of total revenue, showcasing where the future growth engines lie. Looking ahead, investors will be closely watching how Infosys balances its strong deal pipeline—including two mega deals over $2 billion—with the revised growth projections. The firm's ability to convert these Large Deal Wins into revenue amidst persistent macroeconomic headwinds and sustained client caution will be key. With an attractive interim dividend payment slated for November 11, 2026, and an unwavering operating margin of 21%, Infosys is banking on its digital transformation capabilities and AI-first strategy to drive future stability, even as the market remains wary of its lowered guidance.